Americans have a tough time saving. Nearly a third of Americans have zero savings, and around half have less than three months of emergency savings. Equally daunting is how little Americans contribute to 401(k)’s. Dr. Hensley of the National Foundation for Financial Education pointed out in this alarming video that only 11 percent of individuals with a 401(k) are putting enough money away to meet their retirement needs.
The goal of this article is to provide the content and behavioral tips necessary to save.
Understand yourself and how to overcome your own savings obstacles
Saving can be exhausting if you allow it to be. As John Tierney points out in Decision Fatigue, we draw from a chemical in our brain to feed our willpower each time we make a choice. The more frequently we surround ourselves with things we really want and choices we have to make, the more we draw from this chemical. Do not make saving another draining choice you have to make, make saving automatic.
The Marshmallow study best illustrated the challenges we innately face to delay gratification, and the latest Marshmallow study is digging into the particular challenges people face who have had previous experiences that punished them for waiting, complicating the problem even further. We have seen how hard it is for people to pass the test. Do not put yourself through the torture of delaying gratification, make saving automatic.
Become a member of a Bank, Credit Union, or Matched-Savings Program
Find a bank or credit union that offers the lowest fees, or better yet prize-linked savings programs. Do not concern yourself with the interest you are going to earn on your savings account. Rates are low and are likely to stay that way for a while. So, your interest won't add up to much if you do not have a lot of money. What can add up are fees - - so comparison-shop for financial institutions that offer the lowest possible fees.
Another option is matched savings programs such as Earn, who also provide additional support services designed to help low-wage families.
Make saving automatic with a Direct Deposit
A Direct Deposit electronically deposits funds directly into a bank account as a form of payment. This past Bankrate article explains how Direct Deposits work, and dives into further advantages. To be clear, only establishing a direct deposit into your checking account isn’t going to help you much. Work with your HR manager and your financial institution to setup a second and a third direct deposit into your savings account and retirement account. This is sometimes referred to as “split deposits”. Make sure there is no additional fee for setting up or using a Direct Deposit service.
In this research Mindy Hernandez of Innovation@cfed provides behavioral insight on the decision making process“…often the decision we make is not about the ‘optimal choice’ but the one that requires the least amount of effort – the one on the path of least resistance. Defaults are the option you get if you do nothing at all, and they are extremely ‘sticky,’ meaning you are not likely to change the decision (or lack thereof) once it is done…” In other words, by saving first with a direct deposit it would be harder not to save.
The positive results of setting a savings goal and reaching it by making saving automatic is confirmed with research over and over again. According to research reported here by the Electronic Payments Association, 93 percent of employed adults who use split deposit contribute to their savings every month. Conversely, of employed adults who do not use split deposit, 23 percent contribute nothing to their savings.
Make investing automatic with a Direct Deposit
This quality resource on the Department of Labor website empowers employees with useful information about retirement plans, and the power of compound interest. Here is the example the DOL used to illustrate the importance of beginning to invest for retirement at a young age:
“A 20 year old who saves $1,000 a year for 11 years in a row, then stops but leaves it there to earn 7% interest, will have $168,514 at age 65.
However, a 30 year old who starts saving $1,000 a year for 35 years, also earning 7% will have only $147,913 at age 65. Even though the 30 year old has put in more money for more years, it has less time to earn that compound interest.”
In other words, fully match your employer’s 401(k) or 403(b) contribution and do so electronically with a split deposit as soon as you get a job. Make sure there is no additional fee for setting up or using a Direct Deposit service.
America Saves Week is February 25-March 2nd. Now is a great time to pledge or repledge to save. By pledging to save you will commit to a simple savings plan and goal. Research tells us that regardless of income you are more likely to spend less than you earn, save for emergencies, and save for retirement if you have a savings plan.
Set a savings goal, take the pledge, and remember that Direct Deposits matter.
Note - this post was originally written and posted on the America Saves website.
Wednesday, 16 April 2014

Tuesday, 15 April 2014
H&R Block Student Contest: How Big is a Billion?
Americans leave more than $1 billion on the table every year by doing their own taxes. So H&R Block asked teachers to turn the idea of illustrating the $1 billion as a math assignment and submitting real-life examples to illustrate the concept.
Here are just a couple of examples...

...did you know you can wrap $1 billion in dollars around the world 4 times!

Classroom grants of $3,000, $2,000 and $1,000 were awarded across three grade tiers: grades 4th-6th, 7th-9th and 10th-12th. So although the previous examples were very good, they were not the winning entries. You can see the winners of the FaceBook contest here.
Encouraging teens to complete their taxes is of particular importance. A new finding by H&R Block found that teens stress about money, and one of the main causes is the complexity of tax forms. A matter of fact, only 3 out of 100 teens reported filling out an income tax form.

Note - this is a sponsored post I agreed to write because of my support for the content area, the reputation of H&R Block, and the nature of the contest held by H&R Block.
Monday, 14 April 2014
You will love these HOT offers from Groupon! (Ended)
Spice up your week as the Lenten Season is approaching. Saw some great offers and thought I should share it to you. I handpicked these Groupon items with big discounts. You can only find this here exclusively in JuanInvestor. Shop more, sae more! Enjoy and thank me later.
Keratin Blowout Treatment Packages at Headway V.e.r.a Salon at P1,350 (55% discount)
Highlights
- Headway V.e.r.a Salon offers professional salon services to both kids and adults
- Make hair stronger with a keratin treatment
- Trained professionals
- They also offer eyelash extensions, body massages, foot reflexology, hair and makeup, manicure and pedicure services, and waxing services

Or maybe you want to spoil yourself before Friday.. Here's a luscious treat from Gaucho.
Argentinian Roasted Meat Samplers at Gaucho from P490 (51% discount)

Highlights
- The first authentic and traditional Argentinian restaurant in the Philippines
- Serves slow-roasted meats (roasted on a fire pit for 5-6 hours)
- Has a great view for diners
- Located on the 3rd floor of Robinsons Magnolia


Or better yet, indulge in heavy Asian banquet featuring Malaysian, Singaporean, Thai, Vietnamese, Indonesian dishes! Here's an amazing treat from Banana Leaf.
Banana Leaf Lunch or Dinner Treat starting at P550 (45% discount)

Highlights
- Serves authentic Asian cuisines
- Enjoy Malaysian, Singaporean, Thai, Vietnamese, Indonesian dishes
- Redeemable in seven branches
- Banana Leaf has been included in the Philippine Tatler’s list of Best Restaurants for several years


Final Thoughts
Treating one's self (or even family) is a great way to acknowledge and reward thyself for the great work! These treats should be lavish to unwind from a heavy work.However, there are luxuries that are bargained. Find these deals and live happily! I hope you like this post! Share to your friends and have fun! Happy Lenten Season!
Saturday, 12 April 2014
The Vehicle You Deserve To Have


Saturday, 5 April 2014
Start Your FREE Blog in 10 minutes
I must admit that having a blog is complicated as it may seem, but simple once you take the plunge. Most people complain about the cost and intricacy involved in blogging. Fortunately though, simplifying solves the issues. Now think of a blog like driving a car - simple but not easy. Check the Benefits of Blogging.
I'm a Blogger fan and user so I know the experience. Blogger is a "free" platform for blogging. Here you can make a customized website without a penny. It is easy to use and up for grabs to anyone. So why not try it yourself for a couple of months and see if you're into it or not? There's nothing to lose.
Here are the steps to start your FREE blog in 10 minutes:
1. Create a Gmail account.
(Once you already have a Gmail account, proceed to Step 2)
a. Go to "gmail.com"
b. Click "Create an account"
c. Fill up the registration form. Don't forget to tick "Terms of Service"
d. Click "Next Step"
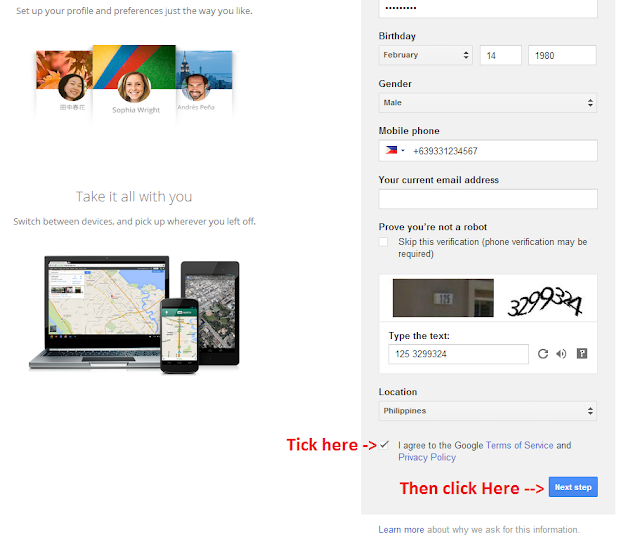
e. A new window appears. Click "Next Step"
f. You now have a Gmail account!
2. Create your Blogger account.
a. Go to "blogger.com" (use another tab or window)
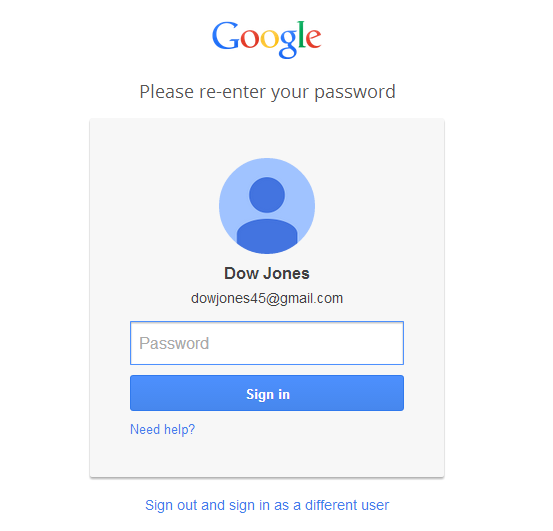
b. Type your Password
c. Click "Sign In"
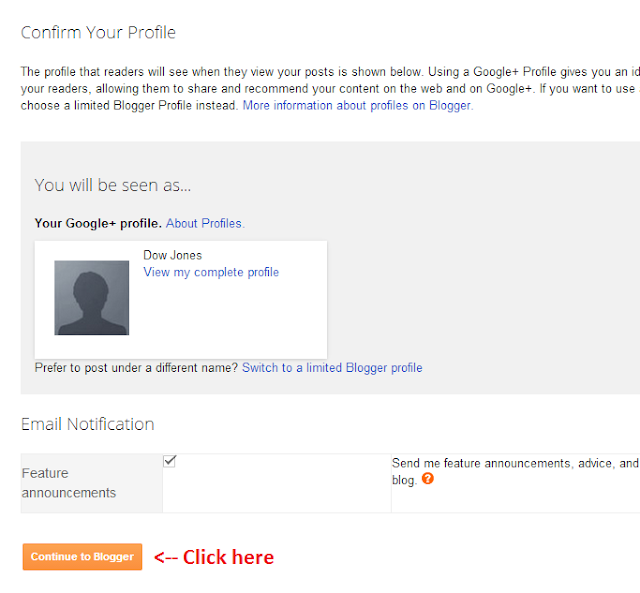
d. A new window appears. Click "Continue to Blogger"
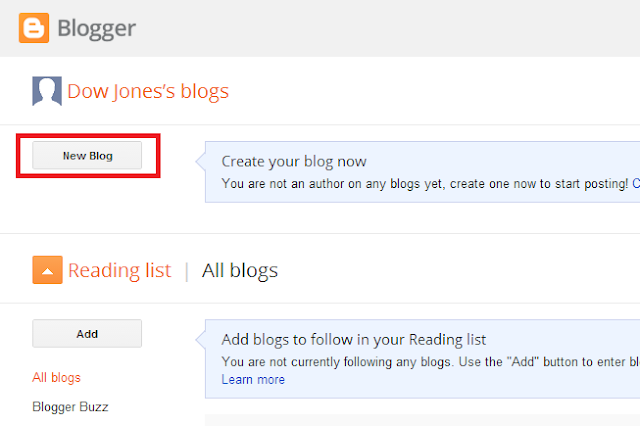
e. Click "New Blog"
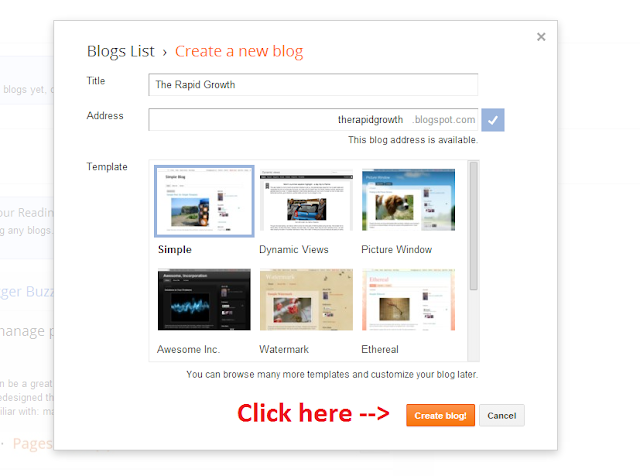
f. A pop-up window appears. Choose your blog title and address wisely. Click "Create Blog"
g. Click "New Blog"
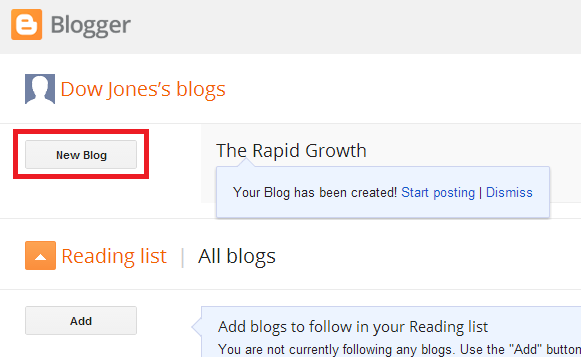
h. Write your first post (Ex. Hello World) and Click "Publish"
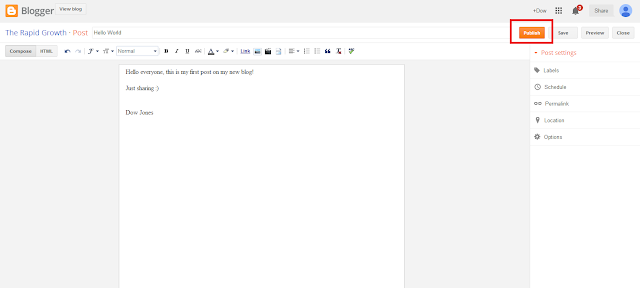
i. It's posted!
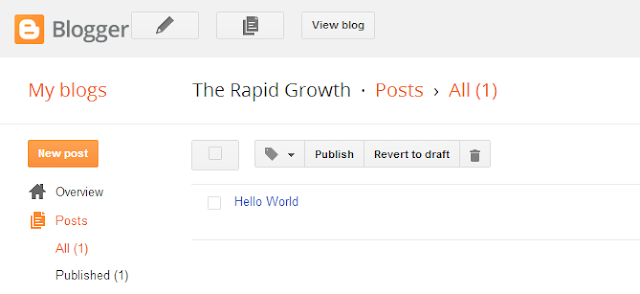
j. See your blog by typing the URL in the address bar
(Ex. therapidgrowth.blogspot.com)
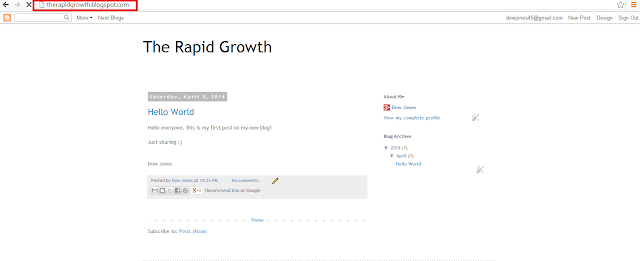
CONGRATULATIONS! You now have a new blog! Did it even take 10 minutes? The rest is customization on your blog layout, color schemes, etc. You can change it anytime and choose what suits you best. Got any questions?
3 Reasons Why You Should Have A Blog

A couple of friends and acquaintances have asked me why I have a blog. Most of them were serious about the question so I answered with modesty, "It's my outlet to express myself and to release my emotions." Surprisingly, the last thing I would hear from them is a silent "Aah."
I never knew (and don't want to find out) what their expression meant. I taught myself recently not to judge other people on their facial expressions or awkward responses. Over-analysis and reading other people's mind is a complete waste of time.
Upon self-examination, I found out these 3 cool benefits of having a blog and why you should have one too. While the initial plan is to monetize my blog, it has changed and dropped it down as a bonus.
3 Benefits of Blogging
1. Writing a blog is a therapy
I don't know with you but since I've started this "blog", I'm amazed with great things that happen to me unexpectedly. And I seriously love it!
Every time I share a post, all the tensions and burden in mind are released, leaving me feel calm and happy. I truly agree that sharing is caring, not only to others but (unknowingly) yourself. Ultimately, you receive a tremendous blessing that you can't find somewhere else - happiness.
Every time I share a post, all the tensions and burden in mind are released, leaving me feel calm and happy. I truly agree that sharing is caring, not only to others but (unknowingly) yourself. Ultimately, you receive a tremendous blessing that you can't find somewhere else - happiness.
2. It improves your communication skills
I don't have an English or a Literature degree but I don't mind the handicap. The way I learned English back in primary and college were sufficient for me to communicate well verbally or literary.
Writing a blog sharpens the edge of my communication skills. Aside from the joy of learning intricate words, it is the enthusiasm of using it that satiates the ultimate learning. "Reading" is bread while "blogging" is the butter. While one can live without the other, there is really nothing better than having both.
Writing a blog sharpens the edge of my communication skills. Aside from the joy of learning intricate words, it is the enthusiasm of using it that satiates the ultimate learning. "Reading" is bread while "blogging" is the butter. While one can live without the other, there is really nothing better than having both.
3. It feels darn good to be appreciated
Setting aside hypocrisy, it is inherent in human beings to be appreciated for the warm things done to other people. Their gratitude, affection and sympathy are priceless. A simple thanks from someone who appreciates what you did is uplifting. However, not to a point of idolatry or obsession. There's only one person who deserves such - Him.
You might want to check out my new post on How to Start your own FREE Blog.
Credits to keepcalm-o-matic.co.uk
Thursday, 3 April 2014
The Golden Rectangle Budget
 |
| 1.618 The Golden Ratio |
This goes back to our previous topic, budget percentages, what is an aesthetically pleasing distribution for those three aspects? I looked to the golden ratio to guide me since it seems to be a magical number. I came up with this:

In truth, charity actually falls under the future because it is our investment for both dunya and akhirat. It is your choice to make.
So, how should we distribute our income in percentages?
Present 62% (food, transportation-gas, rent)
Future 24% (investments, savings, mortgage, charity)
Charity or Past 14% (utility bill, car loan)
If we would like to have the past and charity as separate categories, it would result in:
Present 62%
Future 24%
Past 9%
Charity 5%
It still looks like an ideal budget. In this scenario, what should be categorized into the past would either be utilities or a car loan, as one or the other will fall into the present. Simple and aesthetically pleasing, right?
Subscribe to:
Posts (Atom)