Thursday, 18 September 2014

3 tips to exponentially improve your life

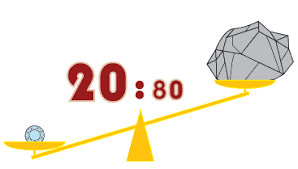
Heard of the Pareto principle?


(Source of image: Here)

It says that 20% of causes are responsible for 80% of effects.

So how do you make small changes that can result in big differences?

Well, here are three to begin with:

  • Always be on time: Respect time. Be ahead of time. But never be late. Apply this to everything you do. And you will always have more than enough time on your hands!

  • Never procrastinate: You got to do what you got to do! So just do it! Keep at it. Just like I pushed myself to write this article :P

  • Make people happy: Friends or Family. Acquaintances or Strangers. Smile at them. Help them out. Make small talk. Make them feel good about themselves. But just spread happiness.

Why don't you try these out?  And share your stories with me!

How Equipment Loans can help your Business Thrive

How Equipment Loans can help your Business Thrive
Image via gettyimages
Different companies enjoy common benefits from capital equipment. Machinery has direct and indirect effects on your bottom line. A new oven and forklift each make your business more productive. Meanwhile, interest and depreciation expense are tax write offs that indirectly improve business profits.

However, your business may not qualify for a general purpose loan to buy much needed equipment. Some obstacles include:

● Lack of operating history: 2 years of profitable operations are preferred by most lenders.

● Little or Poor Credit: A strong payment history under your business tax id may be required. Sole Props must rely on strong personal credit, which puts other assets more at risk.

● Collateral: Many small businesses lack quality collateral coverage. A 1to1 ratio of collateral to loan amount is often needed. Lenders would prefer to not take tables, chairs and food supplies. Heavy machinery and financial assets are examples of higher quality collateral.

Delaying the purchase of new equipment is often not practical, either. Your restaurant may need to quickly boost capacity for lucrative events. Companies need to keep pace with competitors who adapt new technologies. In other cases, manufacturers must replace machinery to maintain production.

So, how can you buy capital equipment with minimal credit, business history or collateral?

Equipment loans are an effective solution.

Equipment financing has mutual benefits for the borrower and lender. These include:

Easy Collateral: 

Your new oven or stamping press serves as quality collateral. Lenders feel more secure making loans backed by specific and valuable assets. Equipment loans also help borrowers overcome collateral shortfalls. A new pizza oven or stamping press is quality collateral for the lender.

Borrower liability is lower with equipment loans, as well. If you default, the machine is simply taken by the lender. However, you may be responsible for a difference in loan balance and equipment value at the time.

Best Practice: Make sure to understand all terms of the loan. You should ensure that collateral beyond the equipment is not pledged.

Trade In Options: 

Technology is constantly changing. A recent breakthrough could make your production presses obsolete. Without liquidity, your business may be at a disadvantage to competitors.
Many equipment leases have trade in clauses to keep pace with tech upgrades. For lenders, trade in options improves the retention of borrowers.

Best Practices: Ask the finance company about prepayment penalties if you pay off the loan early. You should know if there are time minimums before equipment can be traded in.

Faster Approvals: 

Specialty finance companies such as Business Loans Direct have close relationships with manufacturers, which may include special financing offers.

Credit is a minimal or non-factor since the lender knows how the loan will be used. Conversely, general purpose loans pose greater risks for banks. Equipment financing limits collateral and repayment risks to the equipment. The result is easier qualifying and faster approvals.

Ask upfront for the approval criteria. Some lenders may still require certain credit levels or financial ratios. You will save time and money knowing in advance what is needed.

Entrepreneurs who anticipate borrowing needs maximize the ROI of their business loans. You should manage capital equipment for it's full potential. As equipment ages or becomes inefficient, the tax and productivity benefits of new machinery can also be appealing.

You can also check the SBA for special equipment financing opportunities.
Tuesday, 16 September 2014

5 ways to become a star sales person


(Got the image from here!)

Is this your first job in sales? Interested in closing deals right away? Here are a few ways by which you can become a prodigious sales person:

1) Human to Human: Understand that you are selling to a human being and not a company. People buy from other people. So smile at your prospect. Genuinely listen. And be interested in what the other person has to share.

2) Find a common ground with your prospect: Nobody likes a pushy sales person. But everyone likes to find common ground with another person. So once you find what your prospect likes to talk about, you have hit gold mine. Also one must be well read to find common ground. This takes us to my next point. Caveat: If you fake interest, the gold mine can turn into a coal mine.

3) Read: Read as much as possible. Blogs and books. About anything. Don't restrict yourself.

4) Appearance is important: Wear good clothes. Polish your shoes. Apply a classy perfume. Nobody likes to spend time with an unkempt and smelly person.

5) Wish everyone you know on their birthday: Don't you feel good when someone who hasn't spoken to you for an year remembers your birthday?

I personally know someone who does most of this.
His name is Vijayant Dhaka.
And it is inspiring to see him in action!
Follow him @vijayantdhaka

Monday, 8 September 2014

Wanna Be Starting Something

The hardest thing to do is taking that first step. It happens almost every weekend with this blog, when I start with an empty template and not having the slightest idea on what to write about. When it comes to personal finance, budgeting may be the hardest first step. There are so many things needed to be written down that most would probably decide on doing mental accounting.

Humans may be lazy for reasons of energy preservation and by that reason, it may be most logical to break efforts into smaller ones that would be most realistically executed. In budgeting, we have to make a single effort that contribute to starting a budget. That first single effort may be writing our monthly/biweekly/weekly income on top of a piece of paper. You can then build on it on a later day or maybe become motivated to continue and finish it on the same day.

My experience is that once something is started, it builds an emotion inside, a feeling of fixation on wanting to finish it.

Tuesday, 2 September 2014

Our legacy

Our predecessors left cave paintings, books and photographs.

These are difficult to salvage and can be lost to time.

But now we can turn every moment, intimate and otherwise, into a format that can be easily replicated and can last till an electromagnetic burst over rides machines.

Recently iCloud was hacked and compromising pictures of several important people were leaked.

As always, there were those who tried being humorous:


What if you or I were that celebrity?

Would all the money, fame and power make us so thick skinned that we could easily let this go.

Especially if one is an endearing and talented young female actor who is just learning her chops?

Our legacy will be interesting indeed.

Friday, 29 August 2014

Australians Getting Larger Mortgages at a Fixed Rate

Australians Getting Larger Mortgages at a Fixed Rate
Image via gettyimages
The global economic crisis that began in 2008 has had a big impact on the real estate market in Australia. A recovering economy caused mortgage interest rates to drop after an initial period of tight lending regulations. More Australians were apt to choose variable rates as interest fell, but the trends in borrowing have started to change.

More Australians Opt for Fixed Rates

Why are Australians more likely to opt for fixed rates when they apply for a mortgage? Rates were steadily dropping, but it now appears that the historically-low rates that are being offered to home buyers are starting to level out. This means that more people are hoping to lock in the lowest rates possible by opting for a fixed rate.

Variable rates change with the market. This was beneficial for borrowers who were taking out mortgages while interest rates continued to drop. Home buyers were able to take advantage of dropping rates without holding off on their home purchase by opting for a variable rate.

Fixed rates lock in current rates for the duration of the mortgage. These interest rates are ideal when interest is low, and Australia is currently experiencing rates that are expected to be as low as they will get. This is why Australians prefer fixed rates at this point.

Low rates are not the only reason that Australians are opting for this type of interest. Fixed rates are always the same, so people who are dealing with a tight household budget are better able to determine how much housing will cost with a fixed-rate mortgage. A mortgage payment will always be the same with fixed rates.

Average Mortgage Increase

There are several reasons for the steady increase in the amount of the average mortgage. One reason for this trend is the fact that the real estate market is steadily recovering. Homes cost more on average now than they have in the past, so it makes sense that this amount would be increasing.

Another reason is the fact that lower mortgage rates are available. People who are able to take advantage of low rates are able to afford more because of the reduced amount that will be going toward interest payments.

The final reason for higher interest rates is the fact that more people are finding employment across the country. A higher rate of employment means that more people are able to afford a home purchase.

Saturday, 23 August 2014

The Emergency Budget

I was reading an article on twocents.lifehacker and as I reached the comments section, I noticed two awesome inputs suggested by commenters:

1. Create an emergency budget
When I set my budget, I made one assumption. Ceteris Paribus. All other things constant. I would still have my job and all needs remain the same. But there are other scenarios that might happen like losing main source of income, a brand new member in the family, and so on. So, a quick way to live in a state of an emergency is to reduce and eliminate those that can be eliminated to prioritize the fulfillment of needs. Iheartbudget have a great article on this.

2. Have an emergency fund consisting of a "My Car Died" and "My Job Died" fund.
The second suggestion is to categorize emergency fund into two. An emergency if something happens to your car or appliances and an emergency because you lost your job from downsizing, quitting, or retiring. They are both straight forward and I feel by categorizing it, you have a clearer idea of why the money is lying around, and what to do with it once the situation calls it to action.

My Car Died fund should be a cash account fund because it's something that should be ready to use. My Job Died fund can be a mixed portfolio because in the long run, it doubles as a retirement fund. One caution is if the fund is not diversified and you happen to lose your job and the fund is affected by a greater force like inflation or stock market crash.

So, with both points in mind, I guess it's time for me to modify my budget into budgets, and my emergency fund into funds.